Some Known Factual Statements About Kam Financial & Realty, Inc.
Table of ContentsOur Kam Financial & Realty, Inc. IdeasFascination About Kam Financial & Realty, Inc.The smart Trick of Kam Financial & Realty, Inc. That Nobody is Talking AboutA Biased View of Kam Financial & Realty, Inc.Kam Financial & Realty, Inc. Fundamentals ExplainedNot known Factual Statements About Kam Financial & Realty, Inc. Not known Facts About Kam Financial & Realty, Inc.How Kam Financial & Realty, Inc. can Save You Time, Stress, and Money.
If your regional area tax price is 1%, you'll be charged a residential or commercial property tax obligation of $1,400 per yearor a regular monthly home tax obligation of $116. We're on the last leg of PITI: insurance coverage. That's not always a bad point.Bear in mind that wonderful, elegant escrow account you had with your home tax obligations? As with your property taxes, you'll pay part of your house owner's insurance policy costs on top of your principal and interest payment. Your loan provider gathers those settlements in an account, and at the end of the year, your insurance policy company will certainly attract all that cash when your insurance policy settlement is due.
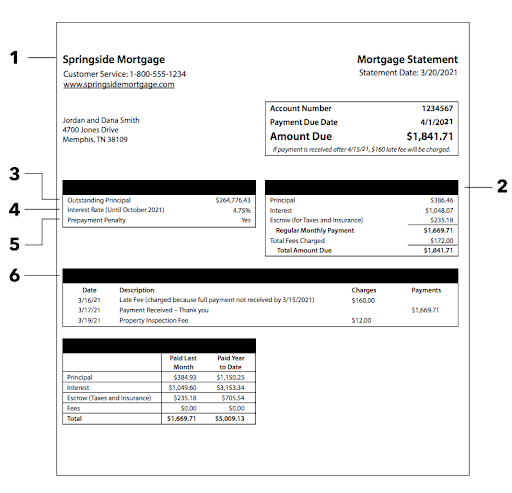
What Does Kam Financial & Realty, Inc. Mean?
It's suggested to shield the loan provider from youwell, at the very least from the opportunity that you can't, or just level don't, make your home mortgage settlements. Of program, that would never ever be youbut the loan provider does not care. If your down payment is less than 20% of the home's rate, you're going to obtain penalized PMI.
If you come from a neighborhood like one of these, don't ignore your HOA fee. Relying on the age and size of your residence and the features, this could include anywhere from $50$350 to the amount you pay every month for your overall real estate expenses. There are many kinds of mortgages and they all charge various regular monthly settlement amounts.
The Kam Financial & Realty, Inc. Diaries

Because you desire to get a home mortgage the smart method, get in touch with our close friends at Churchill Mortgage - mortgage lenders california. They'll walk with you every action of the means to place you on the most effective course to homeownership
Kam Financial & Realty, Inc. Fundamentals Explained
This is one of the most usual sort of home mortgage. You can select a term as much as three decades with the majority of lenders. The majority of the very early repayments pay off the interest, try these out while the majority of the later payments repay the principal (the first quantity you obtained). You can take a table financing with a fixed price of interest or a drifting price. https://www.indiegogo.com/individuals/38029238.
The majority of lenders bill around $200 to $400. This is frequently negotiable. mortgage lenders california.: Table car loans supply the technique of normal settlements and a collection day when they will certainly be repaid. They offer the assurance of recognizing what your payments will certainly be, unless you have a drifting price, in which instance settlement quantities can alter
3 Simple Techniques For Kam Financial & Realty, Inc.
Rotating credit score fundings work like a gigantic overdraft. By maintaining the car loan as reduced as possible at any kind of time, you pay less rate of interest because lending institutions calculate passion daily.
Application fees on rotating credit scores mortgage can be as much as $500. There can be a cost for the day-to-day financial transactions you do with the account.: If you're well ordered, you can pay off your home loan much faster. This also fits individuals with uneven income as there are no fixed settlements.
More About Kam Financial & Realty, Inc.
Subtract the cost savings from the overall lending amount, and you only pay interest on what's left. The more money you maintain across your accounts from day to day, the a lot more you'll save, since passion is calculated daily. Connecting as several accounts as feasible whether from a companion, moms and dads, or various other family members implies even less interest to pay.

Things about Kam Financial & Realty, Inc.
Payments start high, however lower (in a straight line) in time. Charges resemble table loans.: We pay much less interest in general than with a table loan because early repayments consist of a greater settlement of principal. These may suit customers who expect their earnings to go down, for instance, if one companion strategies to give up work in a few years' time.
We pay the interest-only component of our settlements, not the principal, so the payments are lower. Some debtors take an interest-only car loan for a year or more and afterwards switch to a table loan. The typical table lending application charges apply.: We have more money for various other points, such as restorations.
Kam Financial & Realty, Inc. for Beginners
We will certainly still owe the full amount that we obtained up until the interest-only period ends and we start paying back the finance.
The home mortgage note is normally videotaped in the general public documents together with the mortgage or the act of depend on and serves as evidence of the lien on the residential property. The home loan note and the home mortgage or action of trust are 2 different records, and they both serve various legal objectives.